
Philippine Airlines (PAL) and Cebu Pacific are two of the major players in the country’s aviation industry. Both domestic airlines operate under legislative franchises granted by the Philippine government and, pursuant to their respective franchises and applicable laws, have enjoyed certain tax privileges.
Franchise-based VAT exemptions in Philippines
Managing Partner
Gargantiel Law
Quezon City
Under Presidential Decree No. 1590, on 11 June 1978, PAL is granted tax privileges under its franchise, including exemption from value-added tax (VAT) on the importation of aircraft, aircraft equipment, engines, machinery, spare parts and accessories, subject to the conditions prescribed by law.
Similarly, the Bureau of Internal Revenue (BIR) recognised Cebu Pacific’s entitlement to VAT exemption on importing aircraft, engines, equipment and spare parts under Republic Act No. 7151, on 30 August 1991. Under its franchise, Cebu Pacific ipso facto (by that fact) enjoys the tax privileges granted to competing individuals, partnerships or corporations. These franchise-based exemptions illustrate the traditional treatment of tax privileges in the Philippine aviation industry, where a legislative franchise served as an important basis for an airline’s entitlement to certain tax incentives.
Debate on Philippine VAT exemption
The VAT exemption on aircraft imports in the Philippines is significant, as planes are capital assets essential to the operation, expansion and modernisation of air transport services. Philippine tax law recognises this distinction by exempting from VAT the sale, import or lease of passenger or cargo aircraft, including their engines, equipment and spare parts, when used for domestic or international operations.
By reducing the tax burden on aircraft acquisition, the exemption makes it economically feasible for airlines to acquire additional planes, modernise fleets and expand operations, thereby lowering their capital costs while promoting investment, fleet modernisation and competition in the Philippine aviation sector. But this raises an important question: Is entitlement to VAT exemption on aircraft imports necessarily dependent on the existence of a legislative franchise?
NIRC removes franchise VAT dependency
Historically, the tax privileges of major domestic airlines, such as PAL and Cebu Pacific, were tied to their legislative franchises, fostering the misconception that only franchised airlines could claim exemptions, particularly on the imports of aircraft, engines, equipment and spare parts. This is not necessarily the case. Amendments to the National Internal Revenue Code (NIRC) removed franchise dependency for VAT exemption on aircraft imports. The NIRC now exempts from VAT the sale, import or lease of passenger or cargo vessels and aircraft, including engines, equipment and spare parts, when used for domestic or international operations.
The statutory language attaches the exemption to the nature of the transaction and the use of the aircraft, rather than on the possession of a legislative franchise. The legislative franchise should not be treated as the sole legal basis for determining an airline’s entitlement to VAT exemption under the NIRC.
CAB permits support NIRC VAT exemption
The regulatory framework governing air transport operations must likewise be considered. The Philippine Congress has delegated its licensing authority in the aviation industry to the Civil Aeronautics Board (CAB). Under Republic Act No. 776, or the Civil Aeronautics Act of the Philippines, the CAB has regulatory authority over air transport and may issue appropriate certificates and permits to qualified carriers. Therefore, a domestic airline’s authority to conduct air transport operations is subject to compliance with the regulatory requirements, including the issuance of a Certificate of Public Convenience and Necessity (CPCN), where required.
The Department of Finance identifies the CPCN as one of the documentary requirements for an application for VAT exemption covering the import of aircraft, engines, equipment and spare parts under the NIRC. The checklist requires other supporting documents, including an Air Operator Certificate and an authority to import/lease from the CAB.
The CPCN should not be regarded as the source of the VAT exemption itself. The exemption is derived from the NIRC, as amended. The CPCN is regulatory evidence of an airline’s authority to engage in air transport operations and forms part of the documentary requirements supporting an application for VAT exemption. Thus, a domestic airline without a legislative franchise may apply for VAT exemption on imports of qualifying aircraft, engines, equipment and spare parts, subject to compliance with NIRC requirements, and the applicable regulatory and documentary requirements. The absence of a legislative franchise does not, by itself, negate the statutory VAT exemption provided under the NIRC.
But it is important to note that VAT exemption should not be equated with total tax and duty-free imports. Customs duty exemptions have a separate legal basis and may have additional requirements.
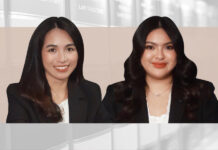
Vanel Andrea Beltejar is managing partner at Gargantiel Law in Quezon City
 GARGANTIEL AND ASSOCIATES
2nd Floor
Times Square Building
No. 57 Examiner St.,
Corner Times St.
West Triangle, Quezon City, Philippines 1104
www.gargantiel.com
Contact details:
T: +63 8355 9623
E: admin@gargantiel.com