
• Law Asia
  • ABLJ
  • CBLJ
  • IBLJ
Register Login Subscribe
  • English
    • 中文 (Chinese (Simplified))
Resources
Awards galleryChina Business Law Directory - PRC law firmsChina Business Law Directory - Cross-border investment guide
Sections
NewsBusiness law digestDispute digestIn-house insightsPractitioners’ perspectivesCorrespondentsMarket watchLegal & regulatory insightsLexicon
Topics
New Company LawIntellectual propertyDispute resolutionCross-border investmentCapital marketsBankruptcy & reorganisation
Law.asia home
Archive
.TV
Awards
CBLJ Forum•Beijing 2026
Events
Jobs
About us
Contact us
Follow Law.asia

China Business Law Journal
English English
  • 中文 中文
China Business Law Journal

    • SECTIONS

      • News
      • Business law digest
      • Dispute digest
      • In-house insights
      • Practitioners’ perspectives
      • Correspondents
      • Market watch
      • Legal & regulatory insights
      • Lexicon

      ABOUT US

      • Editorial board
      • Publisher & credits

      TOPICS

      • New Company Law
      • Intellectual property
      • Dispute resolution
      • Cross-border investment
      • Capital markets
      • Bankruptcy & reorganisation

      RESOURCES

      • Awards gallery
      • China Business Law Directory - PRC law firms
      • China Business Law Directory - Cross-border investment guide

      E-READER EDITION

      ARCHIVE
China Business Law Journal China Business Law Journal
  • Sections
    • News
    • Business law digest
    • Dispute digest
    • In-house insights
    • Practitioners’ perspectives
    • Correspondents
    • Market watch
    • Legal & regulatory insights
    • Lexicon
  • Topics
    • New Company Law
    • Intellectual property
    • Dispute resolution
    • Cross-border investment
    • Capital markets
    • Bankruptcy & reorganisation
  • Videos
  • Awards
  • Jobs
  • Subscribe
  • Events
    • CBLJ Forum • Beijing 2026: Report
    • CBLJ Forum • Shanghai 2025: Report
    • CBLJ Forum • Beijing 2025: Report
    • Other events
  • Law Asia
  • ABLJ
  • CBLJ
  • IBLJ
  • icon
    • Login
    • Register
  • Law Asia
  • ABLJ
  • CBLJ
  • IBLJ

China Business Law Journal
  • Sections
    • News
    • Business law digest
    • Dispute digest
    • In-house insights
    • Practitioners’ perspectives
    • Correspondents
    • Market watch
    • Legal & regulatory insights
    • Lexicon
  • Topics
    • New Company Law
    • Intellectual property
    • Dispute resolution
    • Cross-border investment
    • Capital markets
    • Bankruptcy & reorganisation
  • Videos
  • Awards
  • Jobs
  • Subscribe
  • Events
    • CBLJ Forum • Beijing 2026: Report
    • CBLJ Forum • Shanghai 2025: Report
    • CBLJ Forum • Beijing 2025: Report
    • Other events
English English
  • 中文 中文
  • icon
    • Login
    • Register
Home What's the deal? The homecoming
Post Header Image
  • What's the deal?

The homecoming

30 June 2020
2135
0

A wave of Chinese stocks is poised to exit the US and seek capital back in Shanghai or Hong Kong, following recent fraud allegations of Nasdaq-listed Luckin Coffee and intensifying political tensions. Senior practitioners provide insights into the transactions that are fuelling their return

Navigation


Cayman Islands

Shanghai

Hong Kong

Cayman privatizations back in vogue

Privatizations of public companies incorporated in the Cayman Islands and listed on a major stock exchange are in vogue again for a variety of reasons, financial and regulatory. In the US, for example, the Holding Foreign Companies Accountable Act will prohibit trading in the shares of a company if the Public Company Accounting Oversight Board is unable to conduct an inspection of the audit papers of the company’s foreign auditor for three consecutive years. Chinese companies are a particular target.
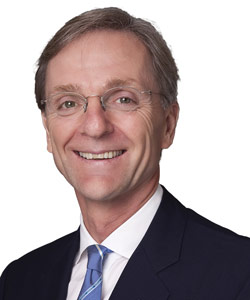
stocks
David Lamb
Consultant
Conyers Dill & Pearman

Privatizations can be effected by: (1) a general offer and compulsory acquisition; (2) a scheme of arrangement; or (3) a long-form or short-form merger.

Long-form mergers have been the predominant method of taking a company private in US markets since the merger provisions were introduced in 2009. But a long-form merger, at least a cash squeeze-out merger, carries a high risk of dissentient shareholders applying to the Grand Court to have the fair value of their shares assessed by the court.

A short-form merger can be undertaken by the buying consortium forming a bid vehicle (Bidco), and the Bidco acquiring shares carrying at least 90% of the voting rights exercisable in general meetings of the target company. The Bidco will then become the parent of the target company and can effect a short-form merger, with the target company being the surviving company in the merger.

Under section 238(1) of the Companies Law, shareholders of the target are entitled to payment of the fair value of their shares, but only upon dissenting from a merger.

The advantage of the short-form merger is that shareholder approval is specifically not required (section 233(7) of the Companies Law), and so is not sought, and the statutory procedural requirements are very different from a long-form merger. There is no vote or decision from which shareholders can “dissent”, and none of the antecedent conditions that are required to be met to exercise appraisal rights in a long-form merger can be satisfied in the case of a short-form merger.

Appraisal rights do not stand in isolation and cannot be crafted out of thin air. Only a member – i.e., a person who is a shareholder entered in the register of members of the company pursuant to section 38 of the Companies Law – of a constituent company in a merger is entitled to an appraisal right. It does not include the holders of American Depositary Shares (ADS) or the holders of depositary instruments.

The exercise of a statutory right to effect a short-form merger, without appraisal rights, at a 90% threshold (albeit voting rights) is consistent with a compulsory acquisition following a general offer (90% acceptances) and to a scheme of arrangement (majority in number of members holding 75% in nominal value of the scheme shares), neither of which carry appraisal rights.

In a retreat from the dizzy days of an appraisal award being made at 235% of the merger consideration (in the matter of Shanda Games FSD 14 of 2016, 25 April 2017), perhaps some semblance of reality has crept into recent appraisal awards where, in one case, the fair value was found to be a mere 1.2% over the merger consideration (in the matter of Qunar, 2019) and a minority discount might be found to apply (Maso Capital Investments Ltd & ors v Shanda Games Ltd [2020]).

However, as the author perpetually stresses, each determination of fair value is highly dependent on its own facts, and upon agreement or disagreement of the valuation models or their components by the valuation experts in each case. Valuation cases do not necessarily form transferable precedents.

From a buy-side perspective, short-form mergers are therefore highly attractive, since they may eliminate the tail-end price risk associated with buying out dissentient minority shareholders at a price which, if applied to the buy-side generally, would potentially make the pricing for the privatization unrealistic.

One example of a short-form merger is the privatization of Jumei International Holding, which was listed on the New York Stock Exchange (NYSE). There have been other public company short-form mergers, but the Jumei transaction is the first two-step merger in the Cayman Islands.

Jumei had a dual-class share structure with the buying consortium holding class B shares (10 votes per share) representing approximately 44.6% of the issued shares and carrying 88.9% of the votes exercisable in general meetings.

The buying consortium had to acquire further shares so that it held at least 90% of the total voting rights to effect the short-form merger. A general offer (the first step) was therefore made for all the issued class A shares (one vote per share) of Jumei, with an acceptance condition that required the tender of sufficient class A shares to enable the buying consortium to hold at least 90% of the total voting rights exercisable in general meetings.

The offer price represented a premium of 14.7% to the closing price of Jumei’s ADS on the NYSE on the last trading day prior to the announcement of the going-private proposal, and a premium of 29.3% to the closing price of Jumei’s ADS on the last trading day prior to the execution of the merger agreement.

After completion of the offer, the remainder of the shares not tendered to the offer were cancelled in a short-form merger (the second step) for the same price as the offer price. Appraisal rights did not apply. Two-step short-form mergers are here to stay.

David Lamb is a consultant at Conyers Dill & Pearman, and acted as the leading Cayman counsel for the buying consortium in Jumei’s privatization. He can be contacted on +852 6469 3377 or by email at david.lamb@conyers.com


Return of red chips and qualification of VIEs

Recently, issues related to the removal of the variable interest entity (VIE) structure, which was very popular five years ago, have received renewed attention. On the one hand, the attraction of the domestic capital market to enterprises has increased. With the good wealth effect of the Shanghai Stock Exchange Science and Technology Innovation Board (Star Market), the promotion of a Growth Enterprise Market (GEM) registration system, and resilient valuations under the COVID-19 pandemic, the domestic A-share market has become a safe harbour as a capital market of global funds.

You must be a subscribersubscribersubscribersubscriber to read this content, please subscribesubscribesubscribesubscribe today.

For group subscribers, please click here to access.
Interested in group subscription? Please contact us.
你需要登录去解锁本文内容。欢迎注册账号。如果想阅读月刊所有文章,欢迎成为我们的订阅会员成为我们的订阅会员。

已有集团订阅,可点击此处继续浏览。
如对集团订阅感兴趣,请联络我们。

Username:
Password:
Lost your password?
  • TAGS
  • AnJie Law Firm
  • Cai Hang
  • Company law
  • Conyers Dill & Pearman
  • COVID-19
  • David Lamb
  • M&A
  • Star Market
  • Stock market
Previous articleOver the peak?
Next articleManaging a crisis
ABLJ editor

RELATED ARTICLESMORE FROM AUTHOR

Shihui Partners Hires Wang Zhining
Market pulse

Shihui recruits former Xiaomi antitrust compliance head 

Creditor Claims Accelerating Shareholder Contributions China
Zhong Lun Law Firm

Creditor claims for accelerating shareholder contributions

By Yi Xiangming and He Lingyu , Zhong Lun Law Firm
China state asset governance
In focus

Turning point

Senior practitioners break down key state asset law revisions, evaluating emerging legal risks in state-owned enterprise restructuring and asset transactions

MOST POPULAR

CBLJ IHCA Feature Image

In-house Counsel Awards 2026

Following months of market research, we have selected these outstanding in-house counsel and their teams

22 June 2026
CBLJ FOTY 2026

China Business Law Awards 2026

28 May 2026
Rising Star 2026 Featured Image

The A-List 2025-26: Rising Stars

26 March 2026

CORRESPONDENTS

China Anti-Cyberbullying Law

Main takeaways from draft Anti-Cyberbullying Law

By Quan Wei, Jingtian & Gongcheng
14 September 2026
Chapter 18A Listing Preparation

Proving core product eligibility for chapter 18A listing

10 September 2026
Creditor Claims Accelerating Shareholder Contributions China

Creditor claims for accelerating shareholder contributions

By Yi Xiangming and He Lingyu , Zhong Lun Law Firm
8 September 2026

FEATURES

Who-owns-AIs-judgment

Who owns AI’s judgment?

Veteran general counsel and scientist discuss a new AI governance paradigm

21 September 2026
Geely IP chief on IP management in the AI era

Innovation shifts gears

The innovation engine is shifting gear. Whoever recalibrates the timing will lead through the next bend.

18 September 2026
China state asset governance

Turning point

Senior practitioners break down key state asset law revisions, evaluating emerging legal risks in state-owned enterprise restructuring and asset transactions

2 September 2026
Veteran general counsel and scientist discuss a new AI governance paradigm
The innovation engine is shifting gear. Whoever recalibrates the timing will lead through the next bend.
Senior practitioners break down key state asset law revisions, evaluating emerging legal risks in state-owned enterprise restructuring and asset transactions

PRACTITIONERS' PERSPECTIVES

Cross-Border Financial Data Governancevideo

Navigating cross-border financial data compliance and overseas regulatory conflicts

By Wang Chufan, Tahota Law Firm
10 September 2026

New regulatory trends shaping compliance management

By Wang Xuechen, Kangda Law Firm
7 September 2026
Banking Supervision Law look-through accountability

Look-through supervision and compliance of shareholders & controllers

By Xiang Fei, Tahota Law Firm
31 July 2026

Lexicon

Lexicon

State-funded companies and corporate governance

31 July 2026
LAW.ASIA

Asia’s leader in legal intelligence

Law.asia is an award-winning portal providing news, analysis and expert advice on business law in Asia to in-house counsel, lawyers in private practice and other business and legal leaders. It features the proprietary editorial content and archives of our premium legal magazines – Asia Business Law Journal, China Business Law Journal and India Business Law Journal – along with videos, law firm listings, awards and much more. Produced by Law.asia Limited, an independent media company, Law.asia is multilingual, offering content in English, Chinese, Japanese and Korean. Find out more.
Follow Law.asia
Law firms Awards Events Legal jobs • Post a job
About us Archive Subscribe Contact us
Please send any press releases, deal announcements, details of new hires, newsletters and any other news items to: news@law.asia
  • Policy on advertising & sponsorship
  • Disclaimer
  • Terms & conditions of use
  • Privacy Policy
© Copyright 2026 Law.asia Limited. All rights reserved.

Follow us on LinkedIn

Follow now
This site is registered on wpml.org as a development site. Switch to a production site key to remove this banner.